THE Buying Process

What is Turn the Key?

Turn the Key Requirements

Am I Eligible for the Philadelphia
Turn the Key Program?

01

To qualify, you need to be a first-time buyer: someone who has never owned a home or has not owned a home for three years leading up to applying to Turn the Key.

02

You must undergo one-on-one homeownership counseling approved by Turn the Key.

03

For eligibility, your household income must not exceed 100% of the Area Median Income (AMI) – corresponding with the size of your household.

Income Guidelines (100% AMI)

Family Size Maximum Annual Household Income
1 $85,900
2 $98,200
3 $110,500
4 $122,700
5 $132,600
6 $142,400
7 $152,200
8 $162,000
More than 8, add per person $9,800
PHDC logo with house roof icon and tagline “Serving Philadelphia Since 1965”
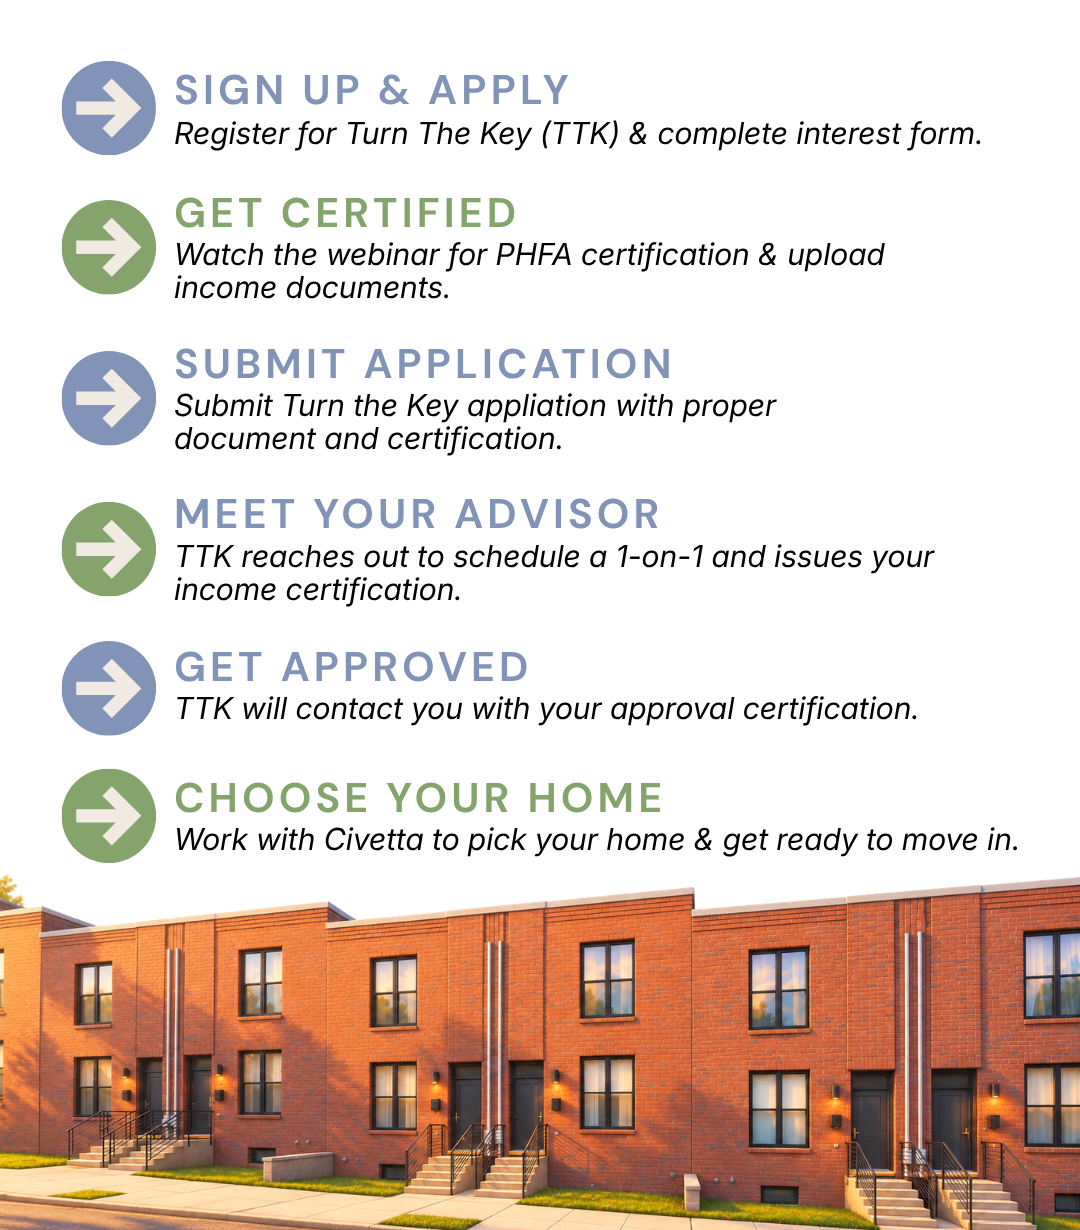
Townhouses with steps: Sign up, get certified, meet advisor, get approved, and choose your home.

Turn the Key Step by Step

Buying a home is easier when you know what to expect. Below, explore how the Turn the Key initiative works, from your initial application to getting your keys.

Row of brick townhouses with a white graphic timeline and arrow icons across the top

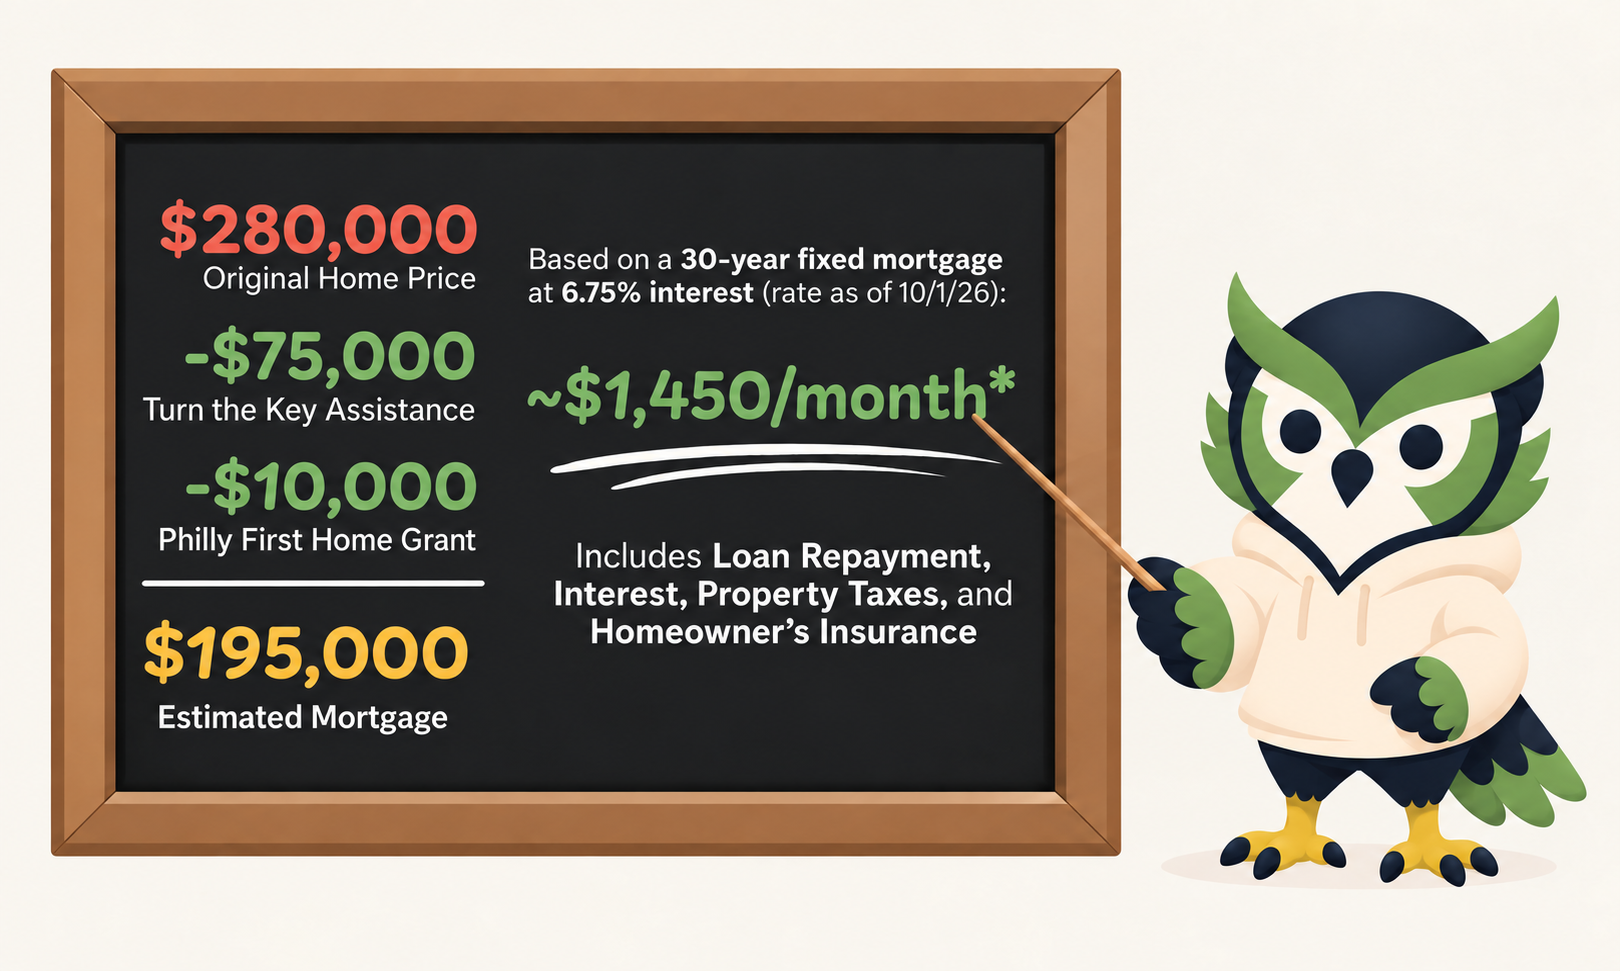
Estimated Monthly

Payment Example

Many Civetta homes qualify for Philadelphia's 10-year tax abatement, which may reduce your property taxes during the abatement period.


*Actual payments may vary based on individual loan terms and interest rates.

Chalkboard with home savings breakdown beside a green-and-black owl mascot in graduation cap and glasses

FAQ

Got Questions? We've answered the ones we hear most from Philadelphia buyers just like you.

  • What is the Turn the Key Initiative?

    Turn the Key is a City of Philadelphia program that helps first-time buyers purchase new homes built on city-owned land. It's part of Mayor Cherelle L. Parker's Housing Opportunities Made Easy (H.O.M.E.) Initiative, managed by the Philadelphia Housing Development Corporation (PHDC).


    Because the city contributes the land, the cost of building comes down. That savings is passed to the buyer rather than the developer. Income-eligible first-time buyers can receive up to $75,000 in mortgage buydown assistance.


    Civetta Property Group is an official Turn the Key development partner, which means we build these homes and guide buyers through the program from first question to closing day.


  • What are the income guidelines for Turn the Key?

    Income guidelines are listed in the chart above. Household income can be no higher than 100% of Area Median Income (AMI) for your household size. Income is calculated using gross income — before taxes and deductions — for all members of the family who will live in the home.

  • If I have bad credit, can I buy a home?

    Possibly, yes. PHDC suggests a credit score around 640, but notes there may be loan products available even if your score is somewhat lower.


    Credit is also a fixable piece of the process. Your housing counselor will review where you stand and help you build a plan — and many buyers who assumed their credit ruled them out found out otherwise in that first session.


    Don't count yourself out based on a number you saw on an app. Let someone look at the full picture.


  • How is my monthly payment kept so low?
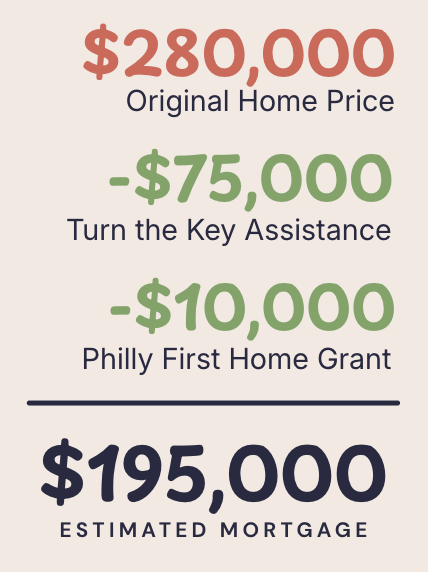
    Mortgage breakdown graphic showing $280,000 original home price reduced by grants to $195,000 estimated mortgage

    The monthly payment is based on a lower initial mortgage cost, through buy-down assistance from Turn the Key assistance and grants, including the Philly First Home grant.
Two people posing with a “Just Got the Keys” cutout sign in front of a Civic Property Management backdrop.

Frequently Asked Questions

  • What is the Turn the Key Initiative?

    Turn The Key Initiative will help up to 1,000 Philadelphia families buy new affordable homes and build equity for their futures. Income-qualified buyers may be eligible for mortgage “buy-down” assistance funds up to $75,000. Learn more about Turn The Key.

  • How are homebuyers selected for Turn The Key?

    You can move through the process by becoming income-certified along with receiving your housing counseling certification and documented mortgage approval. Your information will be sent to developers based on the neighborhoods for which you have expressed interest. Developers will have a member of their sales team contact you directly to tour the various properties.

  • Can grant programs be used toward the purchase of workforce homes?

    Yes, workforce housing works with the Turn the Key Initiative, Philly First, and lender first time homebuyer programs. Programs can be layered.

  • If I have bad credit, can I buy a home?

    We can direct you to resources who can help you improve your credit so that you may qualify in the future.

  • What is the difference between workforce housing and affordable housing?

    Although workforce housing and affordable housing are sometimes used interchangeably, they are not actually the same. Affordable housing in the traditional sense refers to housing that’s affordable to low-income families, typically through government subsidies. Workforce housing is housing that’s affordable to the local workforce, and is aimed at middle-income households that earn too much to qualify for traditional affordable housing subsidies. The availability of workforce housing enables families and city employees to live in their preferred communities, resulting in shorter commute times and improved quality of life.

  • Who is this for?

    This program is for people who want to live and work in Philadelphia. These properties are intended for homeowner occupancy, and are not intended to be utilized as rental properties.

  • What are the deed restrictions on workforce homes?

    • Homebuyers are expected to reside in the home for 15 years as an owner occupant.

    • Home is not permitted to be a rental property or Airbnb.

  • Can I sell my workforce home in the future?

    If the first homebuyer resells the property before the 15-year compliance period, then they must come back to the Land Bank and a.


    a. The Land Bank will calculate the resale price based on the recorded Declaration of Restrictive Covenants (DoRC); Also,


    b. The second homebuyer must be income-qualified by the Land Bank before any sale can happen.


    c. Second homebuyer must accept the 15-year resale restriction.

  • Can I rent out my workforce home?

    No, you cannot rent out the property while you are within the 15-year deed restriction period.

  • May I make exterior and interior renovations on the home?

    Yes, you may make exterior renovations such as painting or interior renovations such as changing the flooring.

  • May I take out a loan against the equity in the home?

    You may refinance to lower the mortgage payment.

  • What documents do I need?

    x